What a Bitcoin Halving Actually Is — and What It Isn't
A Bitcoin halving is a scheduled reduction in the number of new bitcoins the network pays out for each block that miners add to the chain. Every 210,000 blocks — roughly four years at Bitcoin's ten-minute target — the block subsidy is cut in half. It is not a vote, a policy announcement, or a software upgrade: it is arithmetic that every full node verifies independently.
Because the trigger is a block height rather than a calendar date, every "halving date" is an estimate. Blocks arrive slightly faster or slower than ten minutes depending on how much computing power is pointed at the network, so the projected day drifts over time.
Quick Answer: The next Bitcoin halving is expected at block height 1,050,000, currently projected for early 2028 (most trackers point to around March–April 2028). It will reduce the block subsidy from 3.125 BTC to 1.5625 BTC, cutting new issuance from roughly 450 BTC per day to about 225 BTC per day. The most recent halving — the fourth — took place on April 20, 2024 at block 840,000.
Just as important is what a halving is not:
- It does not remove bitcoin from anyone's wallet, and it does not shrink the coins already in existence.
- It does not change the 21 million supply cap.
- It does not directly make mining harder or blocks slower — that is the job of the difficulty adjustment.
- It does not affect transaction fees, which are paid on top of the subsidy and are set by competition for block space.
The Halving Schedule at a Glance
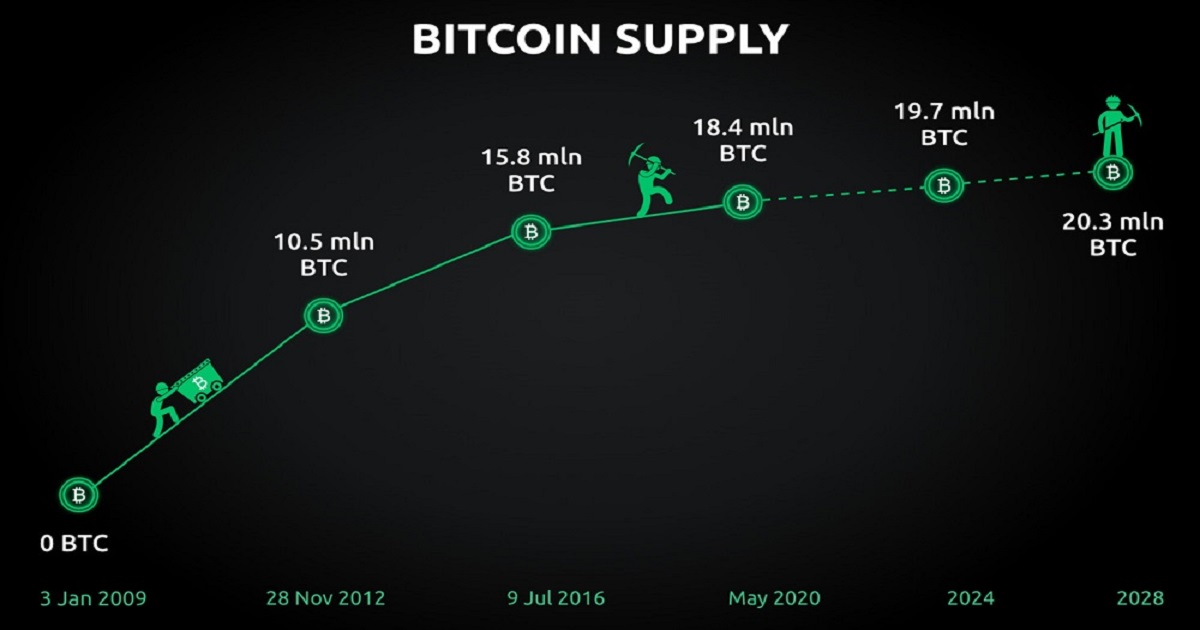
| Halving | Block height | Approximate date | Block subsidy | New BTC per day (avg.) |
|---|---|---|---|---|
| 1st | 210,000 | Nov 28, 2012 | 50 → 25 BTC | 7,200 → 3,600 |
| 2nd | 420,000 | Jul 9, 2016 | 25 → 12.5 BTC | 3,600 → 1,800 |
| 3rd | 630,000 | May 11, 2020 | 12.5 → 6.25 BTC | 1,800 → 900 |
| 4th | 840,000 | Apr 20, 2024 | 6.25 → 3.125 BTC | 900 → 450 |
| 5th | 1,050,000 | Expected in 2028 | 3.125 → 1.5625 BTC | 450 → 225 |
The daily figures assume Bitcoin's target of 144 blocks per day (one block every ten minutes). In practice the network produces slightly more or fewer blocks, which is why the dates in the table are approximations rather than appointments.
Why Bitcoin Halves at All
Bitcoin had to solve two problems at once in 2009: how to issue a new currency without a central issuer, and how to pay the strangers doing the work of securing the ledger. The answer was to pay miners in newly created coins produced by the protocol itself.
A constant issuance rate would have meant permanent, linear dilution. Instead, the subsidy starts high enough to bootstrap a mining industry and then decays geometrically: 50 BTC per block, halved every 210,000 blocks. The result is a supply curve that is public, predictable, and extremely difficult to renegotiate without splitting the network.
Bitcoin's original paper touches on this only briefly, in its "Incentive" section, which notes that mining rewards can eventually be funded entirely by transaction fees and that once a predetermined number of coins has entered circulation, the system can become "completely inflation free." That endpoint describes roughly the year 2140 — not today.
Why the cap lands on 21 million
The 21 million figure is not a single constant written into one line of code; it is the sum of the schedule. The first era issues 50 BTC × 210,000 blocks = 10.5 million coins, and each later era contributes half as much, so the series converges on twice the first era: 21 million.
In Bitcoin Core, the subsidy is calculated by right-shifting 50 BTC by the number of completed halvings (block height divided by 210,000), and it returns zero once that count reaches 64. Integer math rounds the final fractions down to a single satoshi, so the total ever mined ends up a hair below 21 million. That is why "21 million" is best understood as the outcome of a formula rather than a hard-coded switch. New coin issuance is expected to stop around 2140.
How the Halving Works, Step by Step
- The subsidy rule is part of consensus. Every full node independently computes the maximum allowed subsidy from the block's height. A block that pays itself too much is invalid and gets rejected — no committee has to enforce it manually.
- Miners build a block and pay themselves. The first transaction in a block (the coinbase) creates new coins equal to the subsidy, plus the fees collected from every transaction included in that block.
- Height determines the amount. The formula is a right-shift: subsidy = 50 BTC divided by 2^(height ÷ 210,000), with the result truncated to whole satoshis. At height 840,000 that yields 3.125 BTC; at 1,050,000 it yields 1.5625 BTC.
- Timing floats because blocks are not exactly ten minutes. Difficulty retargets every 2,016 blocks (about two weeks) to steer the average back toward ten minutes. More hashrate means faster blocks and an earlier halving; miners shutting down pushes it later.
- Fees are untouched. The halving changes only the subsidy. Because fees also flow to miners, the total block reward does not fall by exactly half.
What Actually Changes After a Halving
- New issuance halves. At roughly 144 blocks per day, a 3.125 BTC subsidy creates about 450 BTC of new supply daily — down from 900 BTC before April 2024. After the 2028 halving it falls to about 225 BTC per day.
- The issuance rate drops below most comparable assets. Annual issuance is now around 164,000 BTC, or under 1% of circulating supply (roughly 0.8%). Estimates for gold's supply growth typically sit in the 1.5–2% range. After 2028, Bitcoin's rate heads toward roughly 0.4%.
- Miner economics tighten immediately. Revenue per unit of hashrate is cut overnight. Higher-cost miners running older machines can turn unprofitable and switch off; difficulty then drifts down over the following retargets, and the network generally rebuilds hashrate later. That pattern has followed every halving so far.
- Fees do not halve — and miner selling pressure does not automatically fall. Only the subsidy is cut. Fees depend on demand for block space and can, in congested periods, dwarf the subsidy; in April 2024, activity around the Runes protocol pushed fees in a single block to well over ten times the new 3.125 BTC subsidy. At the same time, because miners' largest costs are denominated in fiat, a smaller coin reward can mean they sell a larger share of what they earn.
What Happened After Previous Halvings
Three of the first four halvings were followed by new all-time highs within roughly 12 to 18 months: the 2012 halving preceded the late-2013 rally to around $1,100, the 2016 halving preceded the 2017 peak near $19,000, and the 2020 halving preceded the 2021 peak near $69,000. The 2024 halving was also followed by record highs, though they arrived with a longer lag and after deeper drawdowns than the earlier template implied.
It is tempting to read that as a repeatable rule. The defensible version is weaker, for three reasons:
- The sample is tiny. Four observations cannot establish a cycle, and each halving occurred in a very different macro, liquidity, and regulatory environment.
- The mechanism is announced years in advance. If markets are even roughly efficient, a supply change everyone can calculate should be largely reflected in price before it happens — the "already priced in" argument. On a daily basis, 450 BTC of new issuance is small relative to the billions of dollars that change hands in spot markets.
- Correlation is not causation. Halvings coincided with broader crypto cycles, shifts in monetary policy, and waves of retail attention that are hard to separate from the supply change itself.
What can be said with more confidence is narrower: the halving mechanically reduces new supply, and historically it coincided with the early phase of bull markets. It is not a switch that forces prices higher, and there is no widely accepted model that converts a halving into a specific price target.
Halving vs. Related Ideas People Confuse
- Halving vs. difficulty adjustment. The halving changes how many new coins a block pays out. Difficulty adjustment changes how hard it is to find a valid block, retargeting every 2,016 blocks to defend the ten-minute average. Different mechanisms, different clocks — and only difficulty responds to hashrate.
- Block subsidy vs. block reward. The block reward is the subsidy plus all transaction fees in that block. Only the subsidy halves; the total reward can rise or fall depending on fee demand.
- Halving vs. a protocol upgrade or hard fork. A halving requires no code change or coordination — it is the scheduled execution of an existing rule. Altering the schedule would require changing consensus rules that essentially every node and miner follows; a group that did so unilaterally would create a separate chain rather than change Bitcoin.
- Disinflationary vs. deflationary. Bitcoin's issuance declines but never turns negative, which is disinflationary. Deflation refers to a falling general price level or a shrinking money supply. Bitcoin's supply is still growing by hundreds of coins a day.
Common Misconceptions
- "The halving cuts Bitcoin's supply." It slows the growth of supply. New coins are still created every block, and the total keeps rising until around 2140.
- "Bitcoin is deflationary, so it must rise in value." The schedule is disinflationary, and a supply plan is not a price promise. Price depends on demand, and demand is not written into the code.
- "Lower issuance always means less selling pressure." Miners still sell to cover costs, and with a smaller reward they may sell a higher proportion of what they earn.
- "Miners will shut down and the network will stall." Difficulty adjusts to the hashrate actually in use, so the network rebalances within a few retarget periods. Hashrate has reached new highs after every halving so far.
- "The next halving happens on a fixed date." It is triggered by block height 1,050,000. Faster blocks bring it sooner; slower blocks push it later.
Limits of the Halving Narrative
- It says nothing about short-term price direction, liquidity conditions, or regulation.
- A security budget funded mostly by fees after 2140 is untested at that scale, and whether fee revenue can sustain Bitcoin's security is an open debate rather than a settled fact.
- The nominal amounts shrink quickly: by the 2032 halving the subsidy is under 0.8 BTC per block, so the halving's importance shifts from new issuance toward miner revenue and fee markets.
- Lost or inaccessible coins reduce the effective supply, but that is unrelated to the halving schedule.
FAQ
When is the next Bitcoin halving?
It is expected at block height 1,050,000, currently projected for early 2028 (projections generally cluster around March–April). Treat the month as an estimate, because the trigger is a block height and average block times vary.
How many Bitcoin halvings have there been?
Four: November 2012 (50 → 25 BTC), July 2016 (25 → 12.5 BTC), May 2020 (12.5 → 6.25 BTC), and April 2024 (6.25 → 3.125 BTC).
What will the block subsidy be after the next halving?
1.5625 BTC per block, plus whatever transaction fees that block collects.
Does the halving affect transaction fees?
No. Fees reflect demand for block space at a given moment. The halving changes only the subsidy, which is why miners' total revenue can behave very differently from the subsidy itself.
Will the halving push the Bitcoin price up?
There is no mechanical link. Issuance falls, but price depends on demand, liquidity, macro conditions, and how much of the schedule was already anticipated — and the schedule is public years in advance.
Can the halving be delayed or cancelled?
Not without changing consensus rules that almost every node and miner follows. Any unilateral change would produce a separate chain rather than alter Bitcoin's schedule.
What happens when the halvings run out?
Around 2140 the subsidy rounds down to zero and miners rely entirely on transaction fees. Whether fees alone can fund Bitcoin's security at that point is still debated.
Who This Article Is For
This guide is written for readers who want a technically accurate answer to "when is the next Bitcoin halving" and a clear explanation of why the schedule exists — including new investors, self-custody holders tracking supply dynamics, and anyone who has seen confident price predictions attached to halving dates and wants to know what the mechanism actually does.
Who Created This Content?
Barry Stidham has long focused on asset management and portfolio construction. His background spans traditional investment banking and digital asset funds, with expertise in the risk-return characteristics of various asset classes. In the cryptocurrency market, he concentrates on the cyclical patterns of Bitcoin and mainstream assets while tracking growth opportunities in emerging sectors, and he is skilled at integrating macroeconomic variables, liquidity environments, and on-chain behavior into systematic investment frameworks. He has participated in designing multiple fund products and building risk-control systems, with a strong focus on institutional operations and compliance, and he emphasizes discipline and long-term perspective during industry volatility.
Why This Content Exists
Halving questions are time-sensitive, and older answers go stale quickly — many still describe the 2024 halving as a future event. This article exists to give readers a version anchored to block heights rather than headlines, so the schedule stays meaningful as the projected date shifts.
Conclusion
The Bitcoin halving is easier to understand once you stop treating it as a market event and start treating it as a scheduled rule: every 210,000 blocks, the protocol pays miners half as many new coins. The fourth cut already happened in April 2024; the fifth is expected at block 1,050,000, most likely in the first half of 2028. What that does to price in that year is a question the schedule cannot answer — only demand, liquidity, and the broader market can.